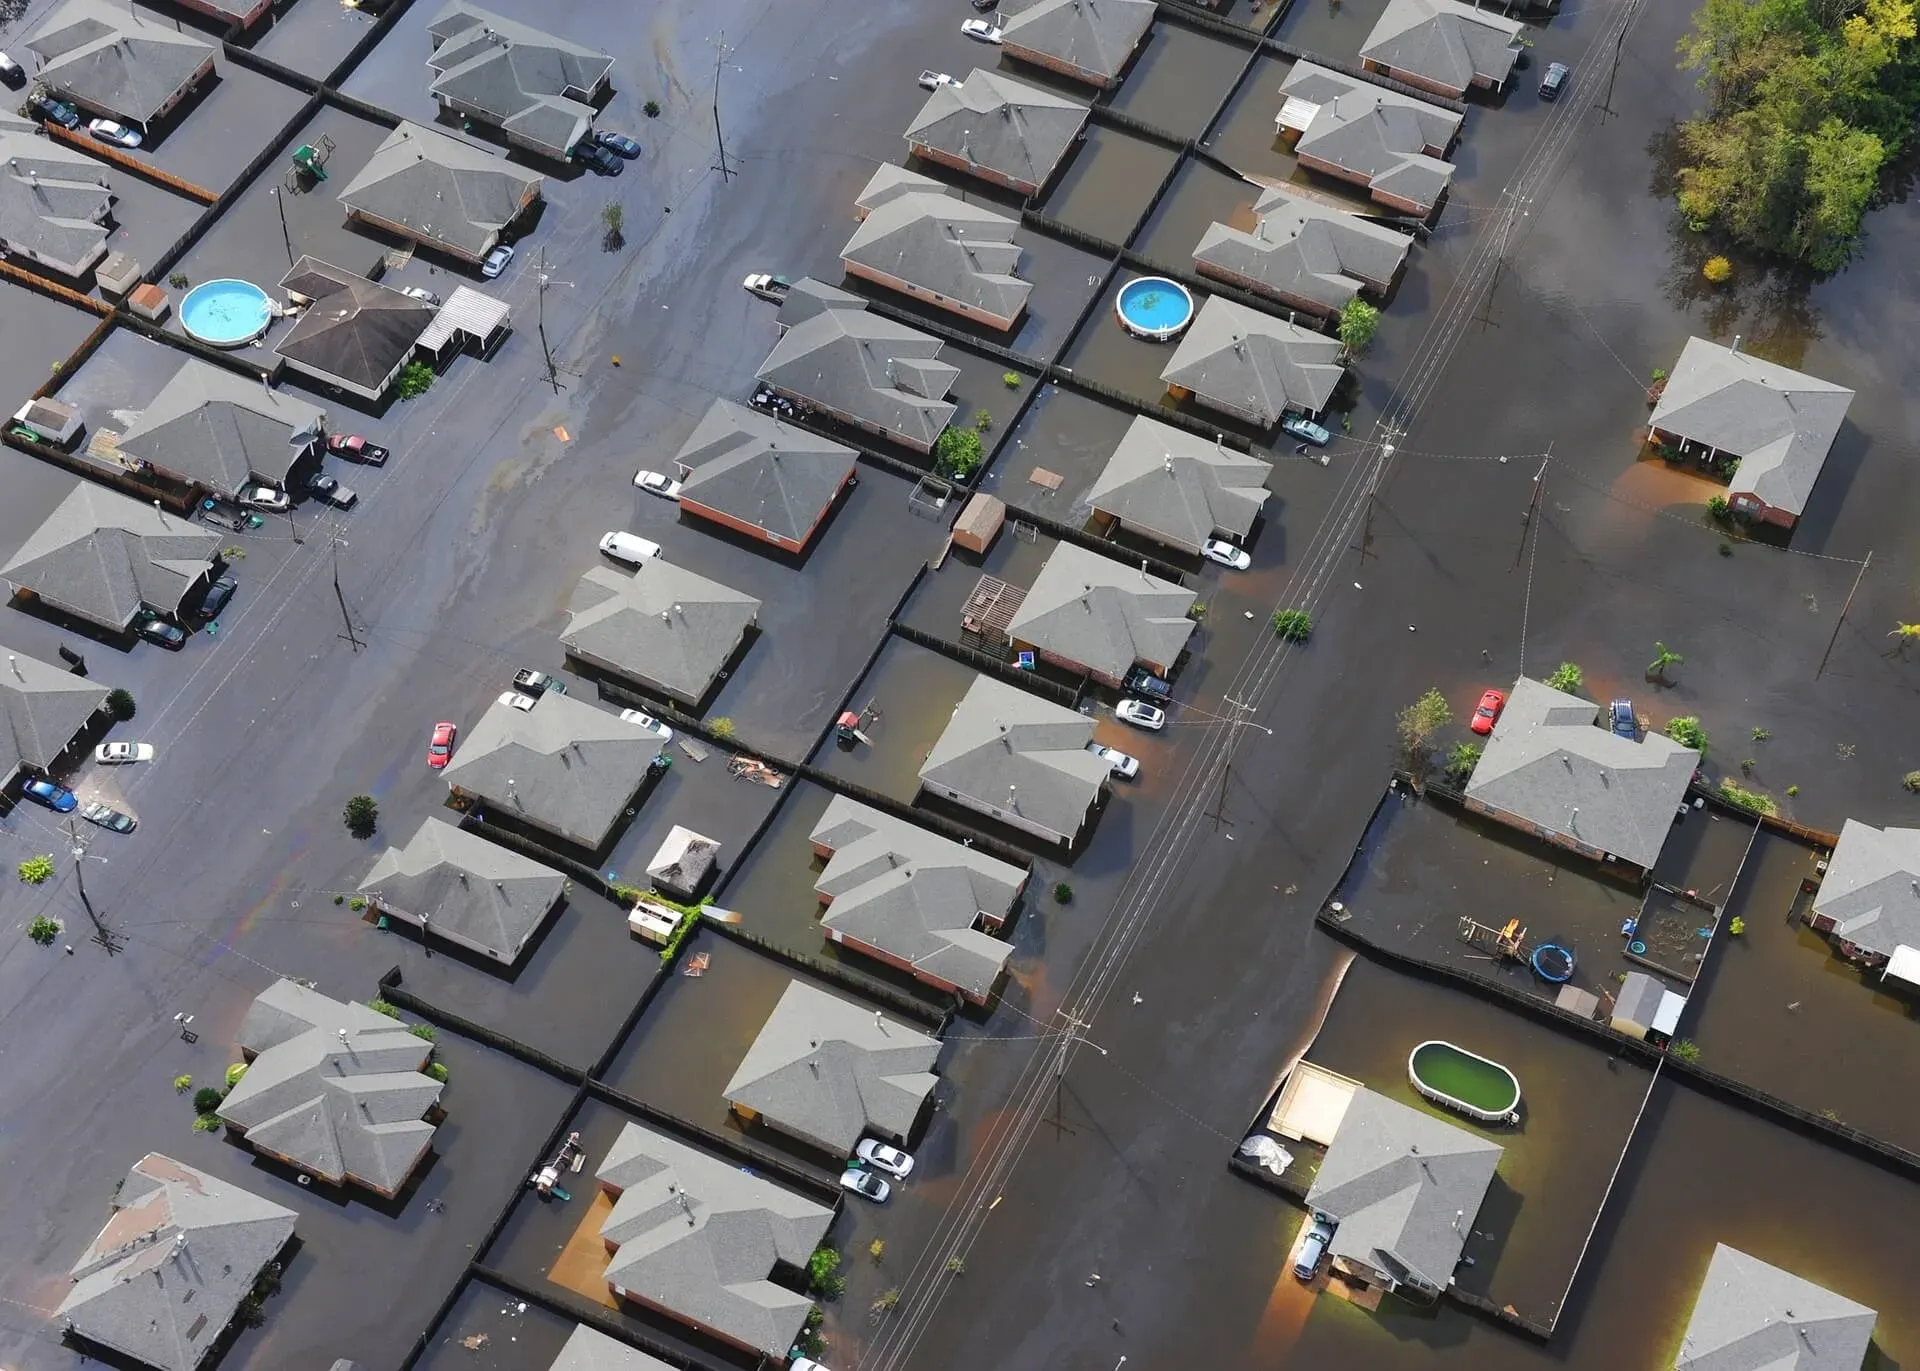
Florida’s heavy rain, hurricane season, and high water table make flood one of the most commonly misunderstood gaps in a homeowner’s protection. The important thing to know: your standard home insurance policy does not cover flood. It’s written separately, and as an independent agency we can help you compare NFIP and private options to find coverage that fits your property.
Do you need flood insurance in Florida?
Many homeowners assume their policy covers flooding. It doesn’t. If you live in a high-risk flood zone, your mortgage lender may require flood insurance. But risk doesn’t stop at the zone line.
What flood insurance covers
A Florida flood policy generally provides two kinds of coverage:
Building coverage
Personal property coverage
How much does flood insurance cost in Florida?
There’s no single price. It depends on your property. We compare the NFIP and private carriers to help you find competitive coverage rather than one option. To set expectations, here’s roughly where Florida flood premiums tend to land. These are general market ranges for context, not a quote:
| Coverage path | Typical annual range | What affects it |
|---|---|---|
| NFIP (federal) | $600 – $1,200 / yr | Standardized building/contents limits; rated under FEMA's Risk Rating 2.0. |
| Private flood market | $500 – $2,500+ / yr | Varies widely by carrier, limits, and property, sometimes lower than NFIP, sometimes broader coverage. |
| Lower-risk (X) zones | from ~$250 / yr | Preferred-risk-style pricing for homes outside high-risk zones, often surprisingly affordable. |
Several things move that number up or down:
- Flood zone classification High-risk (AE/VE) zones generally cost more than low- or moderate-risk zones.
- Home elevation & foundation How high your home sits, and its foundation type, affect the rate.
- Coverage limits & deductible More coverage or a lower deductible raises the premium; you choose the balance.
- Proximity to water Closeness to the coast, a river, or low-lying ground factors in.
NFIP, private market, and whether it’s required
The NFIP is the federal program with standardized limits; private flood carriers can sometimes offer higher limits, broader coverage, or shorter waiting periods. Neither is automatically the better fit. It depends on your home. Here’s how they generally compare:
| Feature | NFIP (federal) | Private flood market |
|---|---|---|
| Coverage limits | Up to $250,000 building / $100,000 contents for a home | Higher limits often available |
| Waiting period | Typically 30 days | May be shorter, depending on the carrier |
| Loss of use (temporary housing) | Not covered | Some policies include it |
| Availability | Widely available, standardized | Depends on carrier appetite and the property |
| Rated by | FEMA’s Risk Rating 2.0 | Each carrier’s own pricing model |
As an independent agency we can quote both sides and walk you through which one makes more sense for your zone and budget.